Author

Clare Louise

Browsing

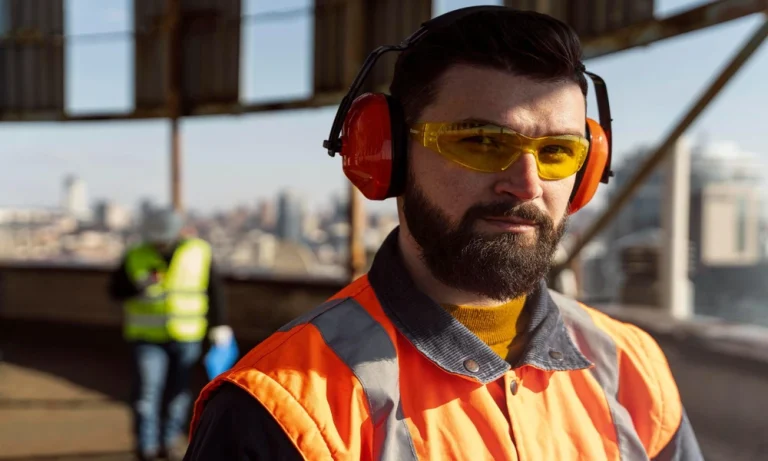
Earplugs remain the default on most sites because they’re cheap, compact, and easy to distribute in bulk. For much of the work on a typical project, that’s a reasonable choice. The problem arises when site conditions shift, whether through a change in machinery, a move to enclosed work, or simply a crew working longer hours near a sustained noise source, and the protection standard doesn’t shift with them. Safety officers reviewing their current provision should watch for five specific signs that earplugs have stopped being adequate for the exposure their crew actually faces.

1. Measured Noise Levels Sit Consistently Above What Earplugs Can Attenuate

Every hearing protector carries a rated attenuation figure, and earplugs generally provide less reduction than well-fitted over-ear protection. Where a sound level meter records sustained levels that, minus the earplugs’ rated attenuation, still leave workers above the permissible exposure limit, the arithmetic alone indicates a need to move to higher-attenuation ear muffs in Singapore rather than continuing with the current provision and hoping fit compensates for the shortfall.

2. Workers Report Ringing or Muffled Hearing After Shifts

Tinnitus or temporary hearing dullness at the end of a shift indicates exposure is reaching the inner ear despite protection being worn. This is a direct, practical signal that the current provision isn’t performing as intended on that site, whether because of insufficient attenuation, poor fit, or inconsistent use. It’s worth treating this feedback as data rather than as a complaint, since workers notice this well before any audiometric test would flag it.

3. Inconsistent Fit Is Undermining Protection in Practice

Earplugs only deliver their rated attenuation when inserted correctly, and correct insertion is harder to achieve and verify than most safety briefings assume. On a large crew with varied training and turnover, a meaningful proportion of plugs are likely to be poorly seated at any given time. Ear muffs offer a more forgiving, visually verifiable fit, which matters considerably for a supervisor trying to confirm compliance across a site without inspecting each worker individually.

4. Work Involves Frequent Removal and Reinsertion of Protection

Tasks requiring workers to move repeatedly between noisy and quiet zones, or to communicate frequently, create a pattern where plugs are pulled out and pushed back in throughout a shift. Each reinsertion risks a poor seal, and in practice many workers stop bothering. Over-ear protection can be lifted and reseated in seconds without the same fit penalty, making it far better suited to this working pattern.

5. Enclosed or Reflective Work Environments Are Amplifying Exposure

Working inside partially completed structures, basements, or tunnels raises effective noise levels through reflection in ways that open-air measurements don’t capture. Hearing protection in Singapore selected on the basis of an open-site assessment can fall short once the same machinery operates within a confined, hard-surfaced space, which makes re-measuring in the actual enclosed conditions an important step before assuming existing provision still suffices.

Key Signs Worth Watching For

  • Measured levels exceeding limits even after subtracting earplug attenuation
  • Workers reporting ringing or muffled hearing at the end of shifts
  • Widespread poor insertion that’s difficult to verify across a crew
  • Work patterns requiring frequent removal and reinsertion of protection
  • Enclosed or reflective spaces raising effective exposure above site assessments

Reassessing Provision Against Current Site Conditions

Hearing damage accumulates without producing an obvious moment of injury, which is precisely why provision tends to lag behind actual exposure on sites where conditions have evolved since the original assessment. Where two or more of these signs are present, a fresh noise assessment against current machinery and working conditions is generally the right next step, followed by matching protection to the exposure that assessment actually records rather than to what was adequate when the project began.

Contact Ansac Technology to review your site’s noise exposure levels and identify the appropriate grade of ear muffs for your crew.

A Farm Loan can support agriculture-related financial needs such as crop production, equipment purchase, irrigation, working capital or other eligible farm expenses. Unlike general-purpose borrowing, agricultural credit often needs to match seasonal income patterns, crop cycles and the specific use of funds.

The right loan structure depends on more than the amount available. Borrowers should consider when the funds are required, how income is expected to arrive, what repayment schedule applies and whether the loan fits the activity being financed.

Since agricultural income can vary across seasons, repayment planning should be done before the loan is accepted.

Start With The Farm Activity, Not The Loan Amount

The amount required for agricultural borrowing depends heavily on what the funds will actually be used for. A farmer may need financing for seeds, fertilisers, labour, irrigation, equipment, livestock, storage, transportation or working capital.

Instead of starting with the amount a lender is willing to provide, begin by estimating the cost of the specific farming activity.

Identify The Time Horizon

Not every agricultural expense follows the same financial cycle.

Seasonal needs may include crop inputs and labour expenses.

Annual requirements may involve recurring farming or livestock costs.

Longer-term requirements can include machinery, irrigation infrastructure or other assets.

Emergency requirements may arise from unexpected farm-related expenses.

The repayment period should be considered alongside this time horizon. A structure designed for a short-term crop expense may not be suitable for a multi-year investment.

Build The Funding Requirement From The Ground Up

Rather than choosing a loan amount first, calculate the expected expenditure.

Start with the major costs:

  • Inputs
  • Labour
  • Transportation
  • Equipment rental
  • Irrigation
  • Storage
  • Other expected expenses
  • A reasonable contingency amount

Then identify the funds already available through savings, existing income or other resources.

Estimated borrowing requirement = Expected farming cost − Available funds

For example, if the expected activity requires ₹3 lakh and ₹1 lakh is already available, the funding gap may be approximately ₹2 lakh.

Borrowing more than this requirement could increase the repayment obligation without necessarily adding value to the farming activity.

Follow The Farm’s Cash-Flow Cycle

Agricultural income does not always arrive at regular monthly intervals. Cash inflows may depend on harvests, crop sales, livestock income, seasonal demand or contract payments.

This makes the timing of repayments particularly important.

Look Beyond The EMI Amount

A monthly instalment may appear manageable when viewed in isolation. The more important question is whether the repayment schedule remains practical during periods when farm income is lower.

  • When the first payment becomes due
  • How frequently repayments are required
  • When major farm income is expected
  • Whether the repayment schedule fits the expected cash inflows

The objective is to consider the repayment obligation alongside the farming cycle rather than treating the EMI as a standalone number.

Check What The Lender Will Require

Agricultural credit can have different eligibility requirements depending on the purpose and product.

The assessment may involve information relating to:

  • Identity
  • Land records, where applicable
  • Income
  • Farming activity
  • Existing financial obligations
  • Repayment history
  • Supporting documentation
  • Lender-specific conditions

Don’t Assume Every Agricultural Loan Works The Same Way

A facility intended for equipment may involve different verification from credit intended for crop-related expenses.

Before applying, review the conditions of the specific product, including its purpose, eligibility criteria and documentation requirements.

Evaluate The Full Cost Before Accepting

The interest rate provides only part of the cost picture.

Depending on the product, borrowers may also encounter processing fees, documentation charges, late-payment charges, insurance-related costs where applicable, prepayment charges or other service fees.

Instead of comparing only the advertised rate, calculate what the borrowing means in actual amounts.

Four Numbers Deserve Attention

Amount sanctioned: The amount approved by the lender.

Net amount received: The amount actually available after permitted deductions.

Total interest: The interest payable according to the loan terms.

Total repayment: The overall amount due across the repayment period.

Looking at these figures together can help farmers understand the financial commitment before taking on the loan.

Make The Loan Fit The Farming Plan

A useful agricultural borrowing decision connects three elements:

The activity determines how much money is required.

The farming cycle influences when income is expected.

The loan structure determines how and when the borrowed amount must be repaid.

Considering all three before applying can help prevent a mismatch between the purpose of the borrowing and the repayment obligation.

Digital Tools Can Help With Loan Management

Using finance apps may make it easier to review account details, track repayments, access statements or manage loan-related information digitally.

The convenience can be useful, especially when branch access is limited, but borrowers should still verify the actual loan terms separately.

Keep Important Information Available

Useful records may include:

  • Sanction letter
  • Loan agreement
  • Repayment schedule
  • Transaction history
  • Customer support details

Digital access should complement proper record-keeping rather than replace it.

Consider Seasonal Risk Before Borrowing

Farm income can be affected by several factors that are difficult to predict.

These may include:

  • Weather
  • Crop yield
  • Market prices
  • Pest damage
  • Input costs
  • Delayed payments

Borrowers should consider how repayment would be managed if income is lower than expected.

Keep Some Contingency Funds

Using the entire loan amount only for planned expenses may leave no flexibility for unexpected costs.

A reasonable contingency can help manage:

  • Additional labour
  • Replanting
  • Repairs
  • Transport changes
  • Emergency inputs

The amount should still remain within the overall borrowing plan.

Watch For These Agricultural Loan Risks

Taking an agricultural loan involves more than checking the interest rate. How the money is used, how the repayment is planned, and how existing obligations are managed can all affect the overall borrowing experience.

1. Keep Farm And Household Spending Separate

Agricultural borrowing should primarily support the purpose for which it was obtained. Using part of the loan for unrelated household expenses may leave insufficient funds for seeds, fertilisers, labour, equipment, or other farming requirements.

A simple way to maintain control is to record expenses separately under categories such as:

  • Farm inputs
  • Equipment and machinery
  • Labour
  • Household spending
  • Loan repayments

This makes it easier to identify where the borrowed funds are going and whether spending remains aligned with the original farming plan.

2. Treat Equipment Loans Differently

Financing machinery requires consideration beyond the purchase price. The equipment should generate enough value through its expected use to justify the overall cost of ownership.

Consider factors such as:

  • Purchase price
  • Fuel consumption
  • Maintenance requirements
  • Repair costs
  • Expected frequency of use
  • Useful life
  • Potential resale value

For equipment that will only be used occasionally, renting may be worth comparing with purchasing. The decision should account for the total cost and expected usage rather than focusing only on ownership.

3. Check Whether Early Repayment Is Flexible

A strong agricultural season may provide an opportunity to reduce outstanding debt earlier than expected. However, the loan terms determine whether this can be done without additional costs or restrictions.

  • Partial prepayment is permitted
  • Full foreclosure is allowed
  • Prepayment or foreclosure charges apply
  • A minimum repayment amount is required

Understanding these conditions in advance can help borrowers assess how much flexibility they will have if their financial position improves.

4. Build A System For Repayment Dates

Missing a repayment date may happen because of poor tracking rather than an inability to pay. Setting reminders can help borrowers prepare funds before the scheduled due date.

Depending on the lender and repayment method, borrowers can use:

  • Calendar reminders
  • SMS alerts
  • App notifications
  • A written repayment schedule

If the repayment is automatically debited from a bank account, maintaining sufficient balance before the due date can also help reduce the possibility of failed transactions and related charges.

5. Plan For Lower-Than-Expected Crop Prices

Repayment planning should not depend entirely on an assumption that crop prices will remain high. Market prices can change between the time a crop is planted and when it is sold.

A more cautious approach is to estimate repayment capacity using realistic or conservative income expectations. This leaves some financial room if selling prices decline or production-related expenses increase.

6. Calculate Existing Debt Before Borrowing Again

A new agricultural loan adds to the household’s overall repayment responsibility. Before taking additional credit, borrowers should review existing obligations, including loans related to:

  • Farm equipment
  • Vehicles
  • Housing
  • Previous crop cycles
  • Other personal or household expenses

The important figure is not just the repayment of the new loan. Borrowers should consider the combined repayment burden of all active loans and assess whether the total remains manageable.

Use A Complete Borrowing Check

Before taking agricultural credit, borrowers can review three areas together: how the funds will be used, how repayment will be managed, and what other debts are already active.

This broader assessment can help prevent situations where a loan appears affordable initially but becomes difficult to manage because of unexpected expenses, lower farm income, or multiple repayment commitments.

Conclusion

A Farm Loan should be planned around the agricultural activity, expected cash flow and repayment schedule rather than only the amount available.

Borrowers should review the purpose, tenure, total cost, seasonal income, documentation and repayment timing before accepting the loan. The broader finance picture also matters because farm borrowing should fit alongside household expenses, existing debt and emergency savings.

A clear borrowing plan can help ensure that the loan supports the farming activity without creating unnecessary repayment pressure.

FAQs

1. Should A Farm Loan Tenure Match The Crop Cycle?

Where possible, the repayment schedule should be reviewed in relation to the timing of expected farm income and the purpose of the loan.

2. Can Farm Borrowing Be Used For Equipment Purchase?

Depending on the product and lender, agricultural credit may be available for eligible equipment or machinery-related requirements.

3. Why Should Farm And Household Expenses Be Tracked Separately?

Separate tracking helps ensure that borrowed funds remain available for the agricultural activity they were intended to support.

4. What Happens If Farm Income Is Delayed?

Borrowers should contact the lender through official channels and review the applicable repayment terms rather than ignoring a due payment.

5. Why Is A Contingency Amount Useful In Farm Planning?

Unexpected costs such as repairs, additional inputs or transport changes can arise during a season, so some financial flexibility can help manage them.
Every day, thousands of people enter commercial offices, shopping malls, residential towers, and industrial facilities without giving a second thought to structural fire risks. We simply assume that if smoke fills a corridor or an alarm sounds, the building’s safety systems will protect us and guide us to safety.

That quiet confidence exists because of rigorous inspection protocols. Behind the scenes, a qualified Fire engineer meticulously audits building layouts, tests safety mechanisms, and verifies strict structural standards. Conducting a thorough assessment protects occupant lives, safeguards physical assets, and keeps property owners compliant with statutory regulations.

Life Safety First: Evaluating Escape Routes and Evacuation Planning

When an emergency strikes, every second counts. The primary goal during any safety evaluation revolves around occupant life safety and how quickly people can exit a burning structure.

A consultant scrutinises the design, width, and accessibility of all escape routes. Emergency exit doors must swing outward in the direction of travel, remain unlocked from the inside, and offer clear passage straight to an ultimate place of safety outside the premises.

Assessments focus on maintaining unobstructed exit passages, verifying that emergency lighting and photoluminescent signage clearly illuminate all evacuation paths, and inspecting fire-rated stairwell enclosures to ensure they effectively resist smoke and flame penetration.

Active Protection Systems: Inspecting Alarms, Sprinklers, and Pumps

Active protection systems detect smoke, alert occupants, and suppress fires actively before emergency crews arrive. A professional evaluates these mechanical and electrical systems during an audit.

  • Smoke & Heat Detectors – Placement density, sensor cleanliness, and signal response times – Triggers immediate building-wide alarms at the earliest sign of combustion
  • Automatic Fire Sprinklers – Water pressure gauges, pipe integrity, and clear head clearance – Discharges water directly over fire origin points to contain heat spread
  • Fire Alarm Control Panel – Fault logs, zone mapping accuracy, and emergency backup power – Directs emergency responders to the exact location of triggered smoke sensors
  • Diesel & Electric Fire Pumps – Automatic start controls, fuel supplies, and discharge pressure – Delivers constant high-pressure water supplies to standpipes and sprinklers

Verifying that these interconnected systems function seamlessly forms a core pillar of maintaining full fire code compliance across commercial properties.

Containment Mechanics: Passive Fire Separation and Compartmentation

While active systems fight flames directly, passive fire protection contains heat, smoke, and toxic gases within a specific area, preventing rapid vertical and horizontal fire spread throughout the building structure.

A certified Fire engineer inspects compartmentation walls, floor slabs, and structural steel coatings. They check whether contractors sealed utility penetrations-such as electrical cables, plumbing pipes, and air conditioning ducts passing through fire-rated walls-using approved intumescent fire-stop sealants and mechanical fire dampers.

If a building owner alters internal room layouts or runs new network cables without sealing wall penetrations properly, smoke will bypass compartmentation barriers quickly, endangering occupants on adjacent floors during an incident.

Smoke Management and Regulatory Compliance Verification

Smoke inhalation presents a far greater immediate danger to occupants than direct flame contact during building fires. Assessing mechanical smoke control systems, smoke curtains, and stairwell pressurisation fans forms a critical phase of the audit process.

Smoke management systems push fresh air into emergency stairwells to keep escape routes smoke-free while extracting toxic gases from large atrium spaces. The consultant tests fan controls, duct dampers, and backup generator power inputs under simulated emergency conditions.

Finally, the consultant audits maintenance logs, annual inspection certificates, and emergency response plans. Demonstrating up-to-date documentation and routine system servicing ensures ongoing fire code compliance, helping property managers avoid hefty statutory fines, operational halts, or insurance claim rejections.

Ensuring Long-Term Safety and Compliance

A professional building assessment provides a vital safety audit that protects lives, preserves property, and maintains legal compliance. By evaluating escape routes, testing active suppression systems, verifying passive fire barriers, and maintaining clear records, property owners create safe built environments. Prioritise safety today and ensure your building stands prepared against fire hazards.

Frequently Asked Questions

How often should commercial building owners conduct a professional fire safety assessment?

Building owners should schedule a comprehensive assessment annually, or whenever undertaking major structural renovations, layout changes, or building usage modifications.

What is the difference between active and passive fire protection systems?

Active protection systems require action or power to trigger (such as alarms, sprinklers, and extinguishers), whereas passive protection contains fire naturally through structural barriers, fire-rated doors, and intumescent wall sealants.

What happens if a building fails a fire safety compliance assessment?

The assessing consultant issues a detailed remediation report outlining specific non-compliance points. Building managers must rectify these safety defects within a designated timeframe to maintain legal building occupation permits.

Contact SHEVS IFT Consultants to safeguard your occupants, protect your property assets, and ensure total regulatory compliance with expert engineering solutions tailored to your building design.

Bike insurance can help two-wheeler owners manage specified financial risks related to accidents, damage, theft, and third-party liabilities, depending on the policy selected. Since motorcycles and scooters are used regularly for commuting, work, and personal travel, understanding the policy before a claim becomes necessary is important.

The right policy should not be selected only on the basis of premium. Coverage type, insured declared value, deductibles, exclusions, add-ons, claim procedures, network garages, and renewal conditions can all affect how useful the insurance is when an unexpected event occurs.

Coverage Type Sets The Foundation

Different insurance structures may provide different levels of protection.

  • Third-party coverage
  • Own-damage coverage
  • Comprehensive coverage

Third-party protection generally addresses eligible liabilities involving others, while broader policies may include specified damage to the insured two-wheeler.

Before comparing premiums, users should understand exactly what type of cover is being offered.

IDV Can Influence The Policy Value

The insured declared value, commonly called IDV, is an important policy component.

It can affect factors such as:

  • Premium
  • Certain claim settlements
  • Overall coverage value

Choosing an unusually low IDV only to reduce the premium may affect the amount available under relevant claims.

The figure should therefore reflect the policy structure rather than being treated simply as a way to lower costs.

Premium Should Be Compared With Protection

A lower premium may look attractive, but cheaper insurance is not necessarily more suitable.

Two policies may differ in:

  • IDV
  • Deductibles
  • Add-ons
  • Exclusions
  • Claim support

A meaningful comparison should use similar coverage levels.

Otherwise, one policy may appear inexpensive simply because it provides less protection.

Deductibles Change The Claim Cost

A deductible is the portion of an eligible claim that may need to be paid by the policyholder, subject to policy terms.

Users should understand:

  • The applicable deductible
  • When it applies
  • How it affects out-of-pocket expenses

A policy with a higher deductible may sometimes have a lower premium.

The trade-off should be understood before purchase.

Add-Ons Should Solve A Specific Need

Optional add-ons may be available depending on the insurer and policy.

These could relate to areas such as:

  • Depreciation
  • Roadside assistance
  • Engine-related risks
  • Other eligible protections

Add-ons can increase the overall premium.

Users should therefore select them according to actual requirements rather than adding every available feature.

An Instant Loan App India Option Is A Separate Financial Decision

An instant loan app india service may provide access to borrowed money, but it should not be treated as a replacement for appropriate insurance coverage.

A loan creates a repayment commitment involving:

  • Interest
  • Fees
  • Instalments
  • Repayment tenure

Insurance is designed to address specified insured risks under policy terms.

Depending entirely on borrowing after an accident can create additional financial pressure, especially when repairs and loan repayments occur at the same time.

Exclusions Should Be Read Before A Claim

Bike insurance does not cover every possible incident.

Policies may exclude certain:

  • Types of damage
  • Circumstances
  • Uses of the vehicle
  • Other specified events

Users should review the detailed policy wording rather than relying only on a short summary.

Understanding exclusions early can reduce confusion during claims.

Claim Procedures Should Be Clear

If an accident or insured event occurs, policyholders may need to follow a specific claim process.

This can involve:

  • Informing the insurer
  • Sharing policy details
  • Providing vehicle information
  • Submitting supporting documents

Users should know where official claim support is available before an emergency happens.

Verified channels should always be used.

Network Garages Can Improve Convenience

Some insurers may provide access to network garages for eligible cashless repairs.

Before purchasing or renewing, users may review whether suitable garages are available near:

  • Home
  • Workplace
  • Frequently travelled areas

Network availability can improve convenience during a claim.

However, users should verify current garage participation when service is actually required.

Cashless And Reimbursement Claims Differ

A cashless claim may allow eligible repair costs to be settled directly between the insurer and a network garage, subject to policy terms.

A reimbursement claim may require the policyholder to pay first and later submit documents.

Understanding both methods helps users know what financial arrangement may be required after an accident.

The claim process should be reviewed before choosing a policy.

Renewal Is A Chance To Reassess Coverage

Policy renewal should not be treated as a routine click.

Users can review:

  • IDV
  • Premium
  • Add-ons
  • Deductibles
  • Personal information
  • Vehicle usage

The right coverage may change as the bike becomes older or the owner’s requirements evolve.

A policy that was suitable several years ago may need adjustment.

No-Claim Benefits Need Proper Context

Some policies may provide a no-claim-related benefit when applicable conditions are met.

Users should understand how the benefit works and how claims may affect it.

The benefit should not discourage a policyholder from making a valid claim when necessary.

Insurance exists primarily to provide specified protection, not simply to preserve a renewal discount.

Vehicle Modifications May Matter

Changes made to a bike can sometimes affect the insurance arrangement.

Depending on the policy and modification, users may need to notify the insurer.

This can relate to certain:

  • Accessories
  • Structural changes
  • Performance modifications

Users should check official requirements before making significant changes to the vehicle.

Documents Should Stay Accessible

Important records may include:

  • Policy document
  • Premium receipt
  • Vehicle details
  • Claim references

Keeping digital copies can make information easier to retrieve during travel or emergencies.

A policy is more useful when its key details are readily available.

Online Payments Need The Same Security Discipline

Policy purchases and renewals may be completed digitally.

Users should verify:

  • Official platform
  • Policy details
  • Premium amount
  • Payment page

OTPs, passwords, UPI PINs, and banking information should never be shared with unknown individuals.

Unusually large discount offers delivered through suspicious links should be treated cautiously.

Compare Policies On Like-For-Like Terms

A fair policy comparison should use similar inputs.

Users should compare:

  • Similar IDV
  • Similar coverage type
  • Similar deductible
  • Similar add-ons

This makes it easier to understand the real difference in premium and service.

Comparing policies with different levels of protection can lead to misleading conclusions.

Everyday Riding Habits Can Influence Requirements

A person using a bike daily for commuting may have different needs from someone who rides only occasionally.

Users may consider:

  • Frequency of use
  • Travel distance
  • Parking conditions
  • Location
  • Vehicle value

Insurance should reflect how the two-wheeler is actually used.

The lowest premium may not provide the right balance for every rider.

A First Recharge Should Not Distract From Policy Terms

A first recharge offer or other promotional benefit may appear alongside digital financial services, but such incentives should not influence the quality of an insurance decision.

The policy should still be judged on coverage, exclusions, deductibles, IDV, claim support, and overall suitability.

Promotional benefits should remain secondary to protection.

Conclusion

bike insurance can provide important financial protection when the policy is selected according to the vehicle, rider needs, and the level of risk being covered.

Users should review coverage type, IDV, deductibles, exclusions, add-ons, network garages, claim processes, and renewal terms before deciding. Borrowing should remain a separate financial decision, and promotional offers should not outweigh policy quality.

A stronger bike insurance choice focuses on clear protection, manageable costs, and dependable claims support rather than simply the lowest available premium.

FAQs

1. What Is Bike Insurance?

Bike insurance is a policy that provides specified financial protection for eligible two-wheeler-related risks according to the policy terms.

2. What Is IDV In Bike Insurance?

IDV generally refers to the insured declared value used for certain policy and claim calculations.

3. Is The Cheapest Policy Always The Best Choice?

No. Coverage, exclusions, deductibles, add-ons, IDV, and claims support should also be compared.

4. What Is A Deductible In Bike Insurance?

A deductible is an amount the policyholder may need to bear as part of an eligible claim, depending on the policy terms.

5. Why Should Bike Insurance Be Reviewed At Renewal?

Vehicle value, usage, policy features, premiums, and coverage requirements can change over time, making periodic review useful.

Key Highlights

  • Flexible cables make compact electronic designs more practical.
  • Reliable cable design improves durability and signal performance.
  • Many industries depend on flexible cables for modern devices.
  • Quality manufacturing supports long-term product reliability.

Introduction

Electronic products continue becoming smaller while offering greater functionality. Designers face the challenge of fitting more components into limited space without sacrificing reliability, performance, or ease of assembly. Every component selected during development contributes to the overall quality and lifespan of the finished product.

Many organisations involved in electronics components manufacturing focus on developing solutions that help engineers create compact, efficient products. Materials that reduce space requirements while maintaining dependable electrical performance have become increasingly valuable across a wide range of industries.

Among these solutions, flexible cables play an important role in modern device design. Their ability to bend, fold, and fit into confined spaces allows manufacturers to produce slimmer products while maintaining reliable electrical connections between internal components.

Why Flexible Cables Are Well Suited for Compact Devices

Modern electronic products require efficient internal layouts, which is why facilities specialising in electronics components manufacturing continually seek practical ways to streamline assembly without compromising build quality. Compact wiring solutions make it much easier to organize internal connections without adding unnecessary weight or bulk to smaller devices.

Unlike rigid wiring, high-grade flexible cables can easily bend around sharp corners and adapt to unique product layouts. Their versatility allows design engineers to maximise available space while maintaining consistent electrical performance throughout the product’s lifespan.

Choosing versatile internal wiring ultimately supports cleaner overall designs that simplify both production and future maintenance. Protecting sensitive connections early in the design stage helps ensure long-term durability across a wide range of commercial applications.

Applications Across Modern Electronics

Consumer electronics represent one of the largest users of flexible cables. Smartphones, tablets, laptops, cameras, and wearable devices all rely on compact internal connections that allow multiple components to communicate efficiently. Flexible routing helps manufacturers create thinner products without affecting functionality.

Medical equipment also benefits from space-saving cable solutions. Portable diagnostic devices, monitoring equipment, and imaging systems require dependable electrical connections while accommodating compact product designs. Reliable cables help maintain consistent performance even where movement or vibration occurs during operation.

Companies specialising in electronics components manufacturing also supply industries such as automotive technology, industrial automation, robotics, and telecommunications. Across these sectors, compact electrical connections support increasingly sophisticated products that require dependable performance in demanding environments.

How Manufacturing Quality Influences Performance

Reliable cable performance begins with precise manufacturing processes. Material selection, conductor quality, insulation consistency, and dimensional accuracy all contribute to dependable electrical performance throughout the product’s service life. Careful production methods also reduce the likelihood of defects during assembly.

High-quality flexible cables are designed to withstand repeated bending without compromising electrical integrity. This durability becomes especially valuable in products that experience regular movement, vibration, or frequent operation. Improved reliability helps reduce maintenance requirements while supporting long-term performance.

Advances within electronics components manufacturing continue driving improvements in cable production techniques. Greater manufacturing precision allows suppliers to produce consistent products that satisfy increasingly demanding performance expectations across multiple industries.

Supporting Future Electronic Innovation

Demand for smaller, smarter, and more capable electronic products continues growing across global markets. Engineers require components that contribute to efficient designs while maintaining dependable operation under everyday conditions. Space-saving electrical connections remain an important part of achieving these objectives.

As technology continues evolving, flexible cables will remain essential for supporting miniaturisation and advanced product development. Their versatility allows manufacturers to integrate more features into compact devices without creating unnecessary design complexity or reducing product reliability.

Continued innovation depends on selecting materials that meet changing engineering requirements. High-quality cable solutions help manufacturers develop products capable of supporting future technological advancements across many different industries.

Conclusion

Compact electronic products require components that combine flexibility, durability, and dependable electrical performance. Thoughtfully designed cable solutions help manufacturers overcome space limitations while supporting efficient production and long-term reliability across numerous applications.

Contact Proterial to explore cable solutions that help bring your next electronics project to life.

When Indian investors sit down to construct a long-term equity portfolio that genuinely reflects conviction in the country’s multi-decade growth story, they almost inevitably arrive at a question that is as much philosophical as it is financial: how much weight to give to the two corporate groups that have, in their very different ways, come to define the ambition and the character of Indian enterprise in the twenty-first century. The scale and diversity of Adani Group Listed Companies – spanning ports, airports, power generation, transmission, green energy, cement, media, and data centres – make the group a proxy for Indian infrastructure at its most expansive. The steadiness and depth of Tata Group Stock – across software, automotive, steel, consumer goods, financial services, and hospitality – make the group a proxy for Indian enterprise at its most diversified and most trusted. Holding both within a single portfolio is not merely a matter of sector allocation but a statement about the kind of India an investor believes in – the India of bold infrastructure creation and the India of patient, values-driven institution building. Understanding the fundamental differences between these two investment philosophies is the starting point for making an intelligent allocation decision between them.

The Infrastructure Bet Versus the Institutional Bet

Investing within the Adani Group at the most demanding levels is often a bet on Indian infrastructure – on the basis that building the physical connective tissue of a rapidly evolving economic system, and owning what makes that connective equipment, will yield tremendous long-term returns. The ports, airports, processing plants and shipping flows operated by the organisation are not just businesses – they are the arteries through which the Indian economy moves goods, people and strength. Investing in the Tata Group, using contrast, is largely institutional speculation – a confidence within the sustainable costs of creating and maintaining a world-class organisation within a governance framework that protects minority shareholders, creates sustainable competitive differences, and excludes extracurricular aggression. payments through money cycles. Both claims could be simultaneously correct, but they reward exclusive types of trades and require specific threat tolerances.

Sector Coverage and Portfolio Diversification

From a pure portfolio construction standpoint, the two groups offer remarkably different sector exposures that complement each other in useful ways. The Adani Group’s listed entities are concentrated in infrastructure, utilities, energy, and resources – sectors whose earnings are primarily driven by government policy, capital expenditure cycles, and the physical development of the country’s logistics and energy networks. The Tata Group’s listed stocks, by contrast, span a far broader range of economic activities – from knowledge economy businesses like IT services to cyclical industrial businesses like steel and commercial vehicles, and from consumer-facing businesses like hospitality to financial services. A portfolio that includes both groups, therefore achieves a diversification across economic drivers – physical infrastructure and policy spending on one side, consumer demand and technology services on the other – that reduces the risk of concentration in any single macroeconomic variable while maintaining robust overall exposure to India’s growth.

Capital Intensity and Cash Flow Generation Compared

One of the most important practical differences between the two groups from an investor’s perspective is the relationship between capital intensity and cash flow generation at different stages of the business cycle. The Adani Group’s infrastructure businesses require continuous and enormous capital investment to build and expand assets, during which free cash flow generation is typically constrained even when operating earnings are strong. The return on this capital is realised over very long horizons as assets generate fee-based revenues across decades of productive life. The Tata Group’s businesses, while also capital-intensive in segments like steel and automotive, tend to have a more varied mix of capital requirements – with the software business generating exceptional free cash flow with minimal capital intensity, the consumer businesses requiring moderate investment, and the industrial businesses occupying the more capital-heavy end. This diversity of capital intensity within the Tata portfolio means that the group as a whole generates more near-term free cash flow relative to its asset base than a pure infrastructure conglomerate.

Promoter Philosophy and Its Impact on Minority Shareholders

Dating between sponsors and minority shareholders is a form of group investment that deserves direct consideration because the philosophy of sponsors – how they reflect concern for public market capital and minority trader rights – shapes every broad choice from dividend policy to takeover strategy, as sponsors and support is oriented in, creates a long-term fitness of the organization instead of a closer short-term monetary extraction This commitment to institutional longevity by the means of minority shareholders is structural security, which is truly valuable. The promoter-driven structure of the Adani Group, while it has enabled rapid and decisive allocation of capital, which may not be possible in a more consensus-driven company, requires minority shareholders to exercise extra caution with related party transactions and allocate capital between public and private.

Dividend Income and the Compounding of Returns

For the long-term investor, dividend income and its reinvestment is one of the most powerful and most underappreciated sources of total return. The Tata Group has a strong tradition of dividend payment across its listed entities, with mature businesses like the IT flagship and several consumer companies distributing regular and growing dividends that, reinvested over the years, compound into a meaningful component of total portfolio returns. The Adani Group’s listed companies, in their current phase of aggressive capacity expansion, tend to retain a much higher proportion of earnings for reinvestment in growth, which is entirely rational given the returns available from their infrastructure projects, but means that dividend income is a much smaller component of current investor returns. This difference in current yield versus future growth potential is one of the key variables that should inform the weighting between the two groups in any investor’s portfolio, depending on their income requirements and reinvestment horizon.

Risk Assessment: What Each Group’s Investors Must Accept

Honest portfolio construction requires a frank acknowledgement of the risks associated with each position. For the Adani Group, the primary risks centre on financial leverage at the holding company level, the concentration of revenue in government-contracted streams that are subject to policy change, the execution risk inherent in managing multiple large infrastructure projects simultaneously, and the sensitivity of long-duration asset valuations to changes in interest rates and financing conditions. For the Tata Group, the risks are more varied in nature but individually less systemic – the automotive business carries cycle risk, the steel business carries commodity price risk, and the IT business carries global technology spending cycle risk. The Tata Group’s individual business risks are largely uncorrelated with each other, which means that the consolidated risk profile is significantly lower than any individual business’s risk might suggest. This diversification of risk within the group is a genuine financial benefit of the conglomerate structure.

Making the Allocation Decision With Clarity

The most sensible approach to allocating between these two great corporate groups is not to choose one over the other but to recognise that they serve different investment purposes within a well-constructed portfolio. The Adani Group’s infrastructure entities provide high-growth, long-duration exposure to India’s physical development – an exposure that is most appropriate at moderate position sizes given the leverage and complexity involved. The Tata Group’s diversified listings provide a lower-volatility, higher-governance, income-generating core holding that can be sized more generously without creating undue concentration risk. Together, they offer the investor a comprehensive expression of India’s economic development – the infrastructure that enables growth and the businesses that grow within that infrastructure. The investor who holds both with clarity about what each is doing in their portfolio is far better served than one who chases either group’s narrative without understanding the distinct roles they play.

In today’s busy and fast-changing world, many people feel confused about their goals, career choices, and personal life. It is common to feel stuck or unsure about what steps to take next. This is where a life coach can make a real difference. A life coach helps you understand your thoughts, set clear goals, and move forward with confidence. Life coach services are designed to support people in finding clarity and direction so they can live a more focused and meaningful life.

Understanding What a Life Coach Does

A life coach is a trained professional who works with you to improve different areas of your life. Unlike a therapist who focuses on mental health issues from the past, a life coach mainly focuses on your present and future. A life coach helps you identify what is holding you back and guides you toward better decisions.

Through simple conversations and guided questions, a life coach helps you explore your strengths, weaknesses, and values. This process allows you to see your life more clearly. With their support, you can start to understand what you truly want and how to achieve it step by step.

Gaining Clarity in Personal Goals

One of the biggest benefits of working with a life coach is gaining clarity about your personal goals. Many people have dreams but struggle to turn them into clear plans. A life coach helps you break down big ideas into small, achievable steps.

When you talk to a life coach, you begin to understand what matters most to you. This might include your relationships, health, education, or personal growth. With clear guidance, you stop feeling overwhelmed and start focusing on what is truly important. Over time, this clarity helps you make better decisions in your daily life.

Finding Direction in Career and Life Decisions

A life coach is also helpful when it comes to career choices and important life decisions. Many people feel lost when choosing a job or changing their career path. A life coach helps you explore your skills and interests so you can choose a direction that fits you better.

Instead of guessing what might work, you learn how to evaluate your options more clearly. A life coach supports you in building a plan that matches your goals and lifestyle. This makes it easier to move forward with confidence instead of fear or confusion.

Building Confidence and Motivation

Another important benefit of a life coach is increased confidence and motivation. When you feel unsure about yourself, it becomes harder to take action. A life coach encourages you to believe in your abilities and stay focused on your progress.

With regular support, you start to develop a more positive mindset. You learn how to overcome self-doubt and stay motivated even when challenges appear. A life coach helps you stay accountable, which means you are more likely to follow through on your goals.

Conclusion

Life coach services can be a powerful tool for anyone who wants to bring more clarity and direction into their life. With the support of a life coach, you can better understand your goals, make smarter decisions, and build stronger confidence. Instead of feeling stuck or confused, you begin to move forward with purpose. In the end, working with a life coach can help you create a more balanced, focused, and fulfilling life.

Hybrid cloud sounds elegant on paper. Keep sensitive workloads on-premise. Push scalable applications to the cloud. Enjoy the best of both worlds.

But here is the reality most IT leaders discover quickly: hybrid cloud without the right connectivity architecture becomes operational friction. Latency spikes. Bandwidth bottlenecks. Complex routing rules. Rising costs.

That is why cloud exchange platforms are becoming a serious consideration for enterprises running hybrid environments in 2026. They are not just connectivity upgrades. They are architectural enablers that turn hybrid complexity into structured scalability.

Let us unpack how cloud exchange works inside hybrid cloud environments and why it is increasingly strategic.

What Hybrid Cloud Actually Means in Practice

Hybrid cloud is not a buzzword. It is an operational design.

It typically involves maintaining on-premise infrastructure, whether in a corporate data centre or colocation facility, while also leveraging one or more public cloud providers.

Some workloads remain on-premise due to regulatory requirements or latency sensitivity. Others migrate to the cloud for elasticity and cost efficiency.

The challenge lies in connecting these environments efficiently and securely.

The Connectivity Problem in Hybrid Architectures

In many hybrid deployments, organisations rely on direct connections or even public internet routing to link on-premise infrastructure with cloud providers.

This works initially. But as additional cloud platforms are introduced or workloads increase, complexity multiplies.

Each direct connection requires provisioning, monitoring and management. Routing policies become layered and difficult to optimise.

Hybrid cloud begins to resemble a patchwork of connections rather than a coherent architecture.

That is where cloud exchange becomes relevant.

What a Cloud Exchange Brings to Hybrid Environments

A cloud exchange acts as a centralised interconnection hub.

Instead of building separate connections from your data centre to each cloud provider, you connect once to the cloud exchange. From there, virtual connections to multiple cloud providers can be established dynamically.

In hybrid environments, this means your on-premise infrastructure gains streamlined access to diverse cloud platforms without duplicating physical circuits.

This architectural simplification reduces operational overhead and improves scalability.

Performance and Latency Optimisation

Hybrid environments often support applications that require low-latency communication between on-premise systems and cloud workloads.

Public internet routing introduces unpredictability. Packet loss and congestion affect application performance.

Cloud exchange platforms typically provide private interconnection pathways. Traffic bypasses the public internet and travels over optimised private routes.

For industries such as finance, manufacturing or healthcare, where milliseconds matter, this performance consistency becomes a competitive factor.

Supporting Multi-Cloud Hybrid Models

Modern hybrid strategies rarely involve a single cloud provider.

Enterprises may run ERP systems in one cloud, analytics workloads in another and disaster recovery in a third.

Cloud exchange architecture centralises access to all these providers.

Instead of provisioning separate direct circuits for each cloud platform, hybrid infrastructure integrates through one interconnection framework.

This reduces duplication and improves network coherence.

Simplifying Network Management

Network teams in hybrid environments often juggle multiple routing policies and monitoring systems.

Each direct cloud connection introduces separate management interfaces and troubleshooting processes.

Cloud exchange platforms consolidate visibility into a unified dashboard. Bandwidth allocation, performance metrics and provisioning workflows can often be managed centrally.

Simplification reduces operational friction and allows IT teams to focus on strategic initiatives.

Security and Compliance in Hybrid Cloud

Hybrid cloud often exists because of regulatory requirements.

Sensitive data may remain on-premise due to compliance obligations. However, cloud services may still process or analyse related data.

Private connectivity through cloud exchange reduces exposure compared to public internet routing.

Segmentation and encryption controls within exchange platforms enhance security posture.

For regulated industries, this architecture provides stronger governance alignment.

Agility and Rapid Provisioning

Hybrid cloud environments must adapt quickly to evolving business needs.

New applications may be deployed in the cloud. Existing workloads may shift between on-premise and cloud platforms.

Cloud exchange platforms allow virtual connections to be provisioned rapidly without installing additional physical infrastructure.

Bandwidth can be scaled up during peak demand and scaled down during quieter periods.

Agility improves when infrastructure adapts in software rather than hardware.

Cost Efficiency at Enterprise Scale

Hybrid architectures can become expensive if not optimised.

Separate connectivity contracts for each cloud provider increase fixed costs. Infrastructure duplication raises maintenance expenses.

Cloud exchange consolidates connectivity. One primary connection supports access to multiple providers.

Over time, this reduces infrastructure sprawl and improves cost predictability.

Strategic IT planning increasingly focuses on total cost of ownership rather than isolated budget lines.

Disaster Recovery and Business Continuity

Hybrid environments often support redundancy strategies.

On-premise systems may replicate data to cloud storage for disaster recovery. Alternatively, cloud workloads may fail back to on-premise infrastructure.

Cloud exchange platforms enable efficient cross-environment routing, supporting resilient architectures.

Business continuity plans become more practical when connectivity supports flexible traffic rerouting.

Automation and DevOps Integration

Modern IT operations rely heavily on automation frameworks.

Hybrid cloud environments benefit from Infrastructure as Code and continuous deployment pipelines.

Many cloud exchange platforms offer API integration, enabling automated provisioning of connections and bandwidth.

This aligns network infrastructure with DevOps workflows.

Hybrid cloud becomes programmable rather than manually configured.

Strategic Awareness in the Market

Interest in cloud exchange is growing among IT leaders researching hybrid optimisation. Early-stage research queries often resemble phrases like “come up with the best topics for a blog post related to this keyword: cloud exchange.”

This reflects broader strategic awareness. Enterprises are beginning to recognise that connectivity architecture determines the success of hybrid strategies.

Connectivity is no longer a background utility. It is a strategic enabler.

When Cloud Exchange May Not Be Necessary

Not every hybrid environment requires centralised interconnection.

If an organisation connects to only one cloud provider and workload scale is predictable, direct connectivity may suffice.

However, most hybrid strategies evolve. New providers are added. Bandwidth requirements fluctuate.

Planning for scalability early prevents costly architectural redesign later.

Final Thoughts

Hybrid cloud is not simply about mixing on-premise and cloud infrastructure. It is about integrating them intelligently.

Cloud exchange enhances hybrid cloud environments by centralising connectivity, improving performance, increasing agility and reducing infrastructure duplication.

In 2026, enterprises that treat connectivity architecture as a strategic design choice rather than a technical afterthought position themselves for sustainable growth.

Because in hybrid environments, success depends not just on where workloads run, but on how they connect.

When searching for air conditioning in ulladulla, experience and reputation matter significantly. Established professionals demonstrate their expertise through consistent quality, positive reviews, and commitment to customer satisfaction.

Honest pricing with no hidden fees builds trust and confidence. Detailed quotes help clients make informed decisions about services. Fair pricing reflects value of expertise, quality, and professional service. Transparent approach to costs demonstrates integrity and respect for clients.

Regular maintenance prevents problems and extends equipment lifespan significantly. Scheduled servicing identifies potential issues before they become emergencies. Preventative care saves money by avoiding costly repairs and replacements. Maintenance programs demonstrate commitment to long-term client relationships.

Clear, upfront pricing enables informed decision-making without surprises. Detailed breakdowns help clients understand costs and value received. Competitive rates reflect commitment to providing accessible professional service. Honest pricing approach shows respect for clients and confidence in value delivered.

Service warranties demonstrate confidence in quality of workmanship. Guarantee protection provides assurance and peace of mind for clients. Standing behind completed work shows commitment to customer satisfaction. Warranty coverage reflects professional integrity and quality standards.

Urgent situations require immediate professional response and expert solutions. 24/7 availability provides peace of mind knowing help is accessible anytime. Rapid response minimizes damage and restores normal conditions quickly. Emergency services demonstrate commitment to serving client needs regardless of timing.

Choosing right professionals impacts results, costs, and long-term satisfaction significantly. Look for licensed, experienced providers who prioritize quality and customer service. Professional standards and dedication to excellence ensure optimal outcomes and lasting value.

Amazon sellers hunt for PPC agencies that deliver results. Reviews reveal patterns in what works and what falls flat. My Amazon Guy Reddit Reviews testimonials highlight specific capabilities that separate strong performers from mediocre ones. Sellers evaluate agencies based on technical execution, communication standards, and measurable outcomes. Knowing which features earn praise helps businesses identify partners worth their time. Reviews cut through marketing claims to expose real performance metrics consistently.

Campaign structure optimization

Strong agencies build campaigns that make sense. They organize ad groups by product category, not random groupings. This matters because proper structure prevents budget waste across unrelated keywords. Reviews praise agencies that create separate campaigns for branded terms versus generic searches. Smart segmentation allows different bid strategies for each product line. Sellers notice improved ACOS within three weeks when the structure gets fixed. Agencies that lump everything together haemorrhage budget on irrelevant clicks. Proper architecture means adjusting bids for high-performers without tanking other products. Clean campaign structure beats throwing money at poorly organized accounts every time.

Responsive account management

Speed wins in PPC management. Sellers rave about agencies that respond within four hours to urgent issues. Quick action prevents runaway spending when campaigns malfunction or competitors shift tactics overnight. Reviews highlight managers who check accounts daily rather than weekly. Problems get caught early. Budget adjustments happen fast. Sellers value agencies that notify them about major changes before implementation. This prevents surprises on monthly invoices. Regular check-ins matter more than fancy dashboards. Agencies that vanish for weeks after initial setup earn harsh criticism. Active management means someone watches campaigns continuously and reacts to market shifts immediately.

Data reporting transparency

Sellers demand clear performance data. The best agencies provide weekly reports showing exactly where money goes. Reports break down spending by campaign, product, and keyword level rather than vague summaries. Reviews praise agencies that explain metrics in plain language. Numbers without context mean nothing. Sellers need to see which products drive profit and which drain resources. Detailed reports reveal patterns that guide strategy decisions. Charts and graphs help, but raw data matters more. Agencies that hide behind pretty presentations while avoiding hard numbers get called out fast. Transparency builds trust. Sellers stick with agencies that show everything, even when results disappoint temporarily.

Keyword research depth

Surface-level keyword research fails. Reviews celebrate agencies that dig deep into search term reports and find hidden opportunities. They identify long-tail keywords competitors miss entirely.

Proper research goes beyond basic tools. Top agencies analyze competitor listings, study customer search patterns, and test unconventional keyword combinations. This work uncovers profitable niches. Sellers praise agencies that eliminate wasteful keywords draining budgets while discovering new terms that convert. Regular keyword audits catch changes in customer behaviour. Markets shift constantly. Agencies that rely on initial research without ongoing refinement leave money on the table. Fresh keyword discovery separates mediocre performers from revenue generators.

Reviews consistently praise agencies that master technical execution while maintaining clear communication. Sellers value partners who combine data expertise with responsive service. Features that earn praise reflect practical capabilities rather than marketing promises. Agencies that deliver these core functions build lasting client relationships and generate positive reviews naturally.